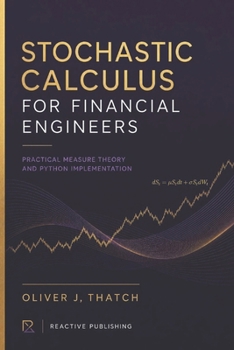
Stochastic Calculus for Financial Engineers: Practical Measure Theory and Python Implementation

Bridge the gap between rigorous mathematical theory and practical quantitative implementation.
Stochastic Calculus for Financial Engineers delivers a clean, unified pathway from foundational measure theory to production-ready Python code. Designed for financial engineers, quantitative analysts, and graduate students, this text strips away unnecessary academic abstraction to focus on the core mathematical machinery required to model, price, and hedge complex derivative contracts.
Rather than treating theoretical probability and algorithmic execution as separate disciplines, this guide demonstrates how measure-theoretic foundations directly inform numerical stability and computational efficiency in modern trading environments.
Inside, you will master:
Measure-Theoretic Foundations: Build a rigorous understanding of probability spaces, filtration, conditioning, and martingales without getting lost in pure-math proofs.
Stochastic Integration: Transition from Brownian motion and It calculus to multidimensional It 's Lemma with practical financial applications.
Partial Differential Equations (PDEs): Connect the Feynman-Kac theorem to parabolic PDEs, boundary conditions, and finite difference schemes for option pricing.
Python Implementation: Translate continuous-time stochastic models into robust vectorized Python code using modern scientific computing libraries.
Numerical Methods & Simulation: Implement Monte Carlo frameworks, variance reduction techniques, and lattice models for path-dependent and American-style options.
Whether you are preparing for quantitative finance interviews, transitioning from software engineering into mathematical finance, or building production pricing models, this book provides the exact balance of theoretical depth and programmatic execution you need.
Customer Reviews
ThriftBooks ® and the ThriftBooks ® logo are registered trademarks of Thrift Books Global, LLC