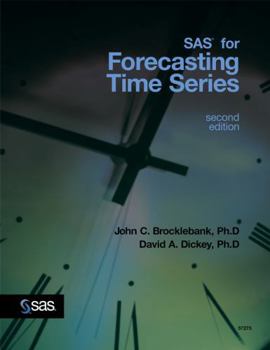
SAS for Forecasting Time Series


Select Format
Select Condition 
Book Overview
Easy-to-read and comprehensive, this book shows how the SAS System performs multivariate time series analysis and features the advanced SAS procedures STATSPACE, ARIMA, and SPECTRA. The interrelationship of SAS/ETS procedures is demonstrated with an accompanying discussion of how the choice of a procedure depends on the data to be analysed and the reults desired. Other topics covered include detecting sinusoidal components in time series models and performing bivariate corr-spectral analysis and comparing the results with the standard transfer function methodology. The authors? unique approach to integrating students in a variety of disciplines and industries. Emphasis is on correct interpretation of output to draw meaningful conclusions. The volume, co-pubished by SAS and JWS, features both theory and practicality, and accompanies a soon-to-be extensive library of SAS hands-on manuals in a multitude of statistical areas. The book can be used with a number of hardware-specific computing machines including CMS, Mac, MVS, Opem VMS Alpha, Opmen VMS VAX, OS/390, OS/2, UNIX, and Windows.
Format:Paperback
Language:English
ISBN:0471395668
ISBN13:9780471395669
Release Date:July 2003
Publisher:John Wiley & Sons
Length:424 Pages
Weight:0.05 lbs.
Dimensions:0.8" x 8.5" x 10.9"
Customer Reviews
2 ratings
Excellent
Published by Thriftbooks.com User , 22 years ago
If you're interested in advanced methods of forecasting time series data using SAS then this is the book to have. It is loaded with examples and interpretation of output as well as a nice concise explanation of theory. Everything you would expect from such renowned authors.
This manual needs a chapter on forecast accuracy.
Published by Thriftbooks.com User , 23 years ago
While the publishers describe SAS for Forecasting Time Series as a manual, the authors have provided more than SAS statements and the resulting outputs. Theoretical explanations, equations, and matrix algebra forms of equations fill the book. This superb manual is the product of the Research and Development Director of Analytic Solutions at SAS and of the Professor of Statistics who was the co-inventor of the Dickey-Fuller test. In addition to the coverage of the essential univariate and multivariate time series analysis topics (e.g., ARIMA models), the authors included entire chapters or large portions of chapters on: Cointegration, State Space Modeling, Spectral Analysis, and Data Mining.My only disappointment with this manual was the lack of an entire chapter on forecast accuracy. Four pages of references did not include a single reference to articles about forecasting competitions. The authors could have: (1) held back recent data in their examples (2) made forecasts with their best models (3) explained how to identify significant changes over time in error terms, standard errors, and in correlations (4) explained when and how to re-calculate model parameters (5) discussed the choice of unbiased forecast accuracy measures for comparing forecasts from ARIMA and regression models.
Copyright © 2026 Thriftbooks.com
Terms of Use | Privacy Policy | Do Not Sell/Share My Personal Information | Cookie Policy | Cookie Preferences | Accessibility Statement
ThriftBooks ® and the ThriftBooks ® logo are registered trademarks of Thrift Books Global, LLC
ThriftBooks ® and the ThriftBooks ® logo are registered trademarks of Thrift Books Global, LLC