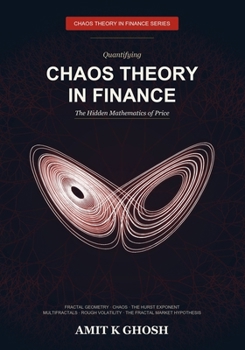
Quantifying Chaos Theory in Finance: The Hidden Mathematics of Price
No Customer Reviews

The graduate-level companion to the Chaos Theory in Finance series - a rigorous, self-contained treatise on the mathematics that governs rough, memory-laden markets.
Quantifying Chaos Theory in Finance develops fractal geometry, nonlinear dynamics, long memory and multifractal models from first principles and turns them on real price data. Where the first book taught the trader's craft, this one builds the machinery underneath it - every algorithm derived, every figure generated from the mathematics it illustrates, every method shown on a fully worked numerical example.
Inside you will master:
Fractal and Hausdorff dimension, self-similarity and the box-counting measure of a price seriesDeterministic chaos - the logistic map, strange attractors, Lyapunov exponents and Takens embedding - and whether markets truly are chaoticThe Hurst exponent, fractional Brownian motion and DFA estimation of long memoryMultifractals, the MMAR, MF-DFA and the Markov-switching multifractal modelRough volatility, heavy tails, the Fractal Market Hypothesis and Hawkes-process microstructureWritten for quantitative researchers, advanced students and the mathematically serious trader. Part of the Chaos Theory in Finance series.
Format:Paperback
Language:English
ISBN:B0H9JMTCVX
ISBN13:9798188058951
Release Date:July 2026
Publisher:Independently Published
Length:272 Pages
Weight:1.05 lbs.
Dimensions:0.6" x 7.0" x 10.0"
Customer Reviews
0 rating
Copyright © 2026 Thriftbooks.com
Terms of Use | Privacy Policy | Do Not Sell/Share My Personal Information | Cookie Notice | Cookie Preferences | Accessibility Statement
ThriftBooks ® and the ThriftBooks ® logo are registered trademarks of Thrift Books Global, LLC
ThriftBooks ® and the ThriftBooks ® logo are registered trademarks of Thrift Books Global, LLC