< Back to Search Results
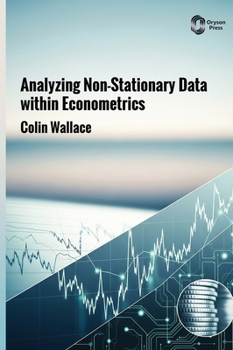
Analyzing Non-Stationary Data within Econometrics
No Customer Reviews

Analyzing Non-Stationary Data within Econometrics addresses a critical challenge in modern economic analysis: the prevalence of non-stationary processes in time-series data. Understanding and correctly modeling these dynamics is paramount for deriving accurate equilibrium relationships, forecasting, and policy implications. Traditional econometric techniques often fail in the presence of non-stationarity, leading to spurious results and unreliable inferences, thus necessitating specialized approaches like co-integration and error correction models.This book systematically explores fundamental concepts from time-series analysis, stochastic processes, and Brownian motion, providing empirical context. It delves into linear transformations, error correction models, and the properties of integrated processes, including spurious regression and unit root testing methodologies. Further, it comprehensively covers co-integration theory, its applications in both single equations and systems of equations, and robust regression analysis techniques designed for integrated variables, alongside discussions on asymptotic theory and Wiener distribution.This essential resource is tailored for graduate students, researchers, and practitioners in econometrics, economics, and finance seeking to master the analysis of non-stationary time series.
Format:Hardcover
Language:English
ISBN:B0H9Y1H5P7
ISBN13:9798887156477
Release Date:August 2026
Publisher:Oryson Press
Length:390 Pages
Weight:1.96 lbs.
Dimensions:0.9" x 7.0" x 10.0"
Customer Reviews
0 rating
Copyright © 2026 Thriftbooks.com
Terms of Use | Privacy Policy | Do Not Sell/Share My Personal Information | Cookie Notice | Cookie Preferences | Accessibility Statement
ThriftBooks ® and the ThriftBooks ® logo are registered trademarks of Thrift Books Global, LLC
ThriftBooks ® and the ThriftBooks ® logo are registered trademarks of Thrift Books Global, LLC